A Texan With $200,000 in Home Equity Keeps All of It in Bankruptcy. Here’s What Every Other State Protects.
By Andrew Reichek, Real Estate Investor | Data reviewed October 3, 2026 | 50 states + D.C.
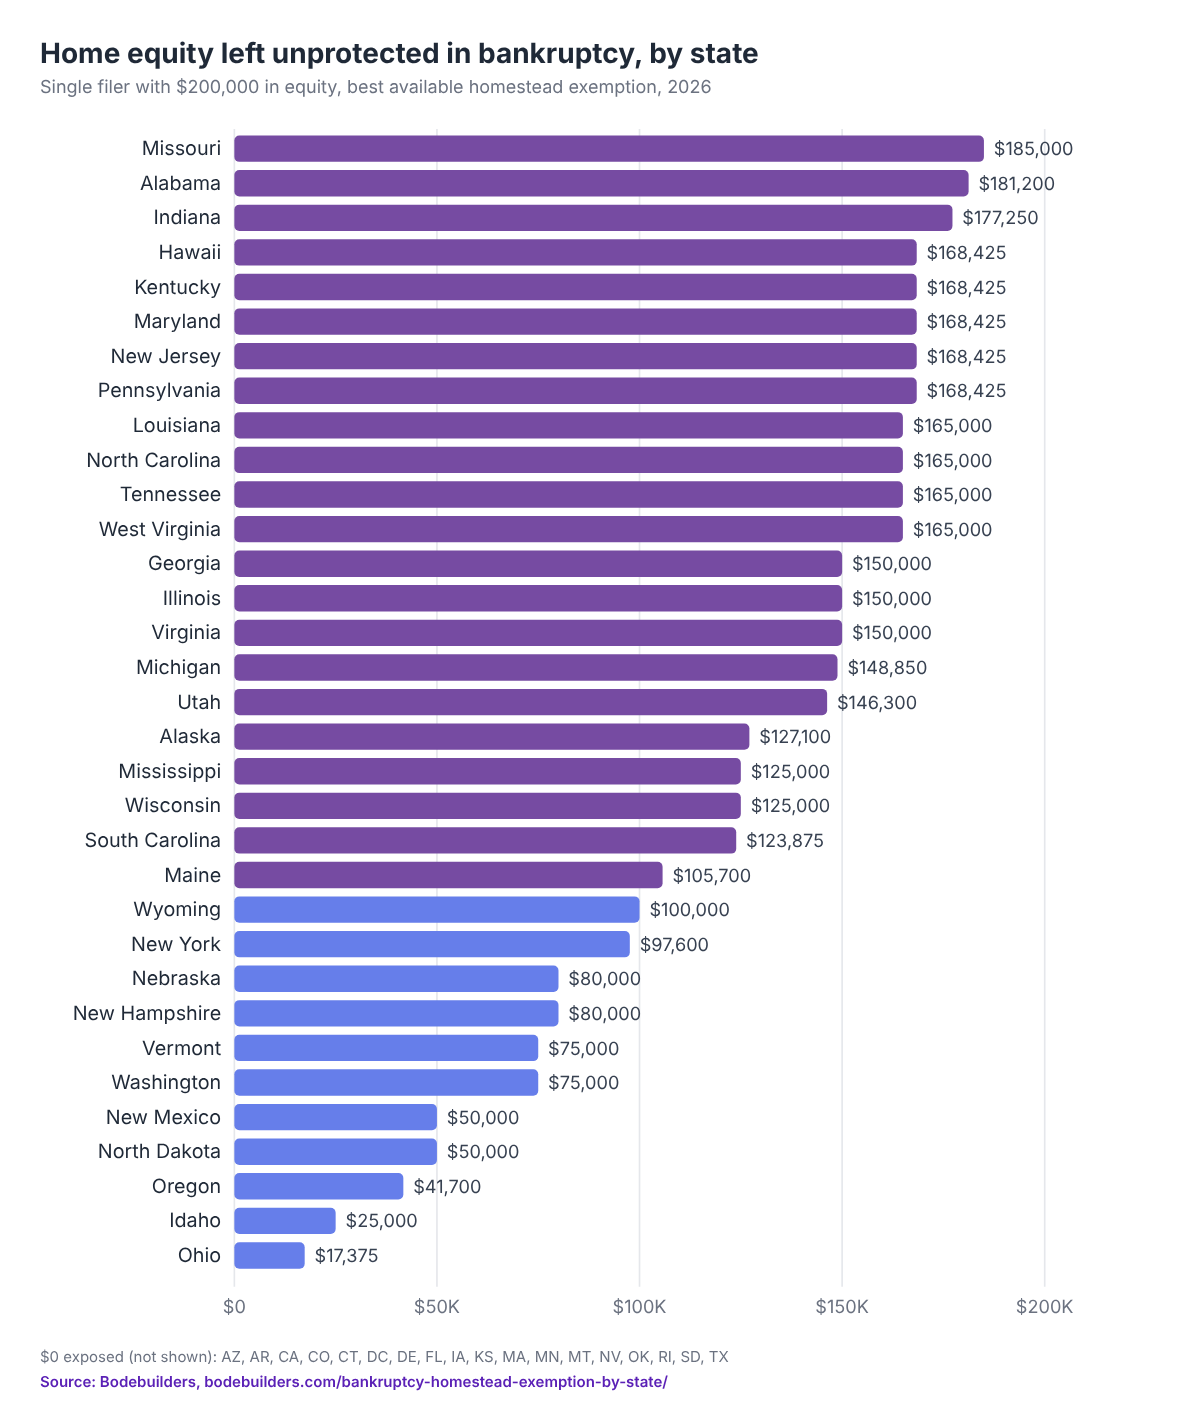
Bankruptcy homestead exemptions by state range from nothing at all in New Jersey and Pennsylvania to unlimited in Texas, six other states and Washington, D.C. A Bodebuilders review of every state homestead statute plus D.C., current as of October 3, 2026, found that a single filer with $200,000 in home equity keeps every dollar of it in 18 jurisdictions, Texas included. In 22 states, more than half of that same equity falls outside the exemption. Missouri leaves the most exposed: $185,000.
- The median protection across all 51 jurisdictions is $120,000, using the better of the state or federal option.
- 15 states protect $50,000 or less of a home’s equity.
- Texas courts saw 14,027 Chapter 13 filings in the 12 months ending June 30, 2026, about 6.5% of the national total.
What Does “Unprotected” Equity Actually Mean in Bankruptcy?
A homestead exemption is the slice of home equity creditors can’t touch. Equity is what’s left after the mortgage and any other liens. Anything above the exemption is fair game. But how “fair game” plays out depends on the chapter.
In Chapter 7, a trustee can sell the house, hand the owner the exempt amount in cash, and pay creditors from the rest. That’s the scenario people fear.
Chapter 13 works differently. The owner keeps the house. But the repayment plan has to pay unsecured creditors at least what they’d have received in a Chapter 7 liquidation. That’s the “best interest of creditors” test in 11 U.S.C. §1325(a)(4). So in Chapter 13, every dollar of unprotected equity raises the floor on what the plan must pay. It’s the reason a $200,000 equity cushion can mean a modest plan in Texas and a crushing one in Missouri.
And when a Chapter 13 filer sells, the same math decides how much of the sale check goes into the plan. Bodebuilders covers the sale process step by step in selling a house during Chapter 13.
How Much of $200,000 in Equity Each State Leaves Exposed
Same filer. Same house. Same $200,000 in equity. The only thing that changes is the state line. Eighteen jurisdictions protect all of it and don’t appear below. Everyone else leaves something on the table.
Check Your Own State’s Numbers
Pick a state, enter the equity, and see the split. The calculator uses the single-filer homestead amount and picks the federal list when a state allows it and it pays more.
Estimate only. Married couples, age or disability enhancements, wildcard exemptions and how title is held can change the result. A bankruptcy attorney can run the real numbers.
Bankruptcy Homestead Exemption by State: The Full 2026 Table
Amounts are for a single filer. “Best option” is the higher of the state amount or the federal $31,575, where the state lets filers choose the federal list. Exposure columns show how much equity sits outside that protection at three equity levels.
| State | State homestead exemption | Federal list allowed? | Best option | Exposed at $100K | Exposed at $200K | Exposed at $300K | Acreage / lot limit |
|---|---|---|---|---|---|---|---|
| Alabama | $18,800 | No | $18,800 | $81,200 | $181,200 | $281,200 | 160 acres |
| Alaska | $72,900 | Yes | $72,900 | $27,100 | $127,100 | $227,100 | None listed |
| Arizona | $437,600 c | No | $437,600 | $0 | $0 | $0 | None listed |
| Arkansas | Unlimited a | Yes | Unlimited | $0 | $0 | $0 | ¼ acre urban / 80 acres rural |
| California | $371,500 to $743,700 c | No | $371,500 | $0 | $0 | $0 | county-based |
| Colorado | $250,000 | No | $250,000 | $0 | $0 | $50,000 | None listed |
| Connecticut | $250,000 | Yes | $250,000 | $0 | $0 | $50,000 | None listed |
| Delaware | $200,000 | No | $200,000 | $0 | $0 | $100,000 | None listed |
| District of Columbia | Unlimited | Yes | Unlimited | $0 | $0 | $0 | None listed |
| Florida | Unlimited | No | Unlimited | $0 | $0 | $0 | ½ acre urban / 160 acres rural |
| Georgia | $50,000 | No | $50,000 | $50,000 | $150,000 | $250,000 | None listed |
| Hawaii | $20,000 ($30,000 head of family or 65+) | Yes | $31,575 | $68,425 | $168,425 | $268,425 | None listed |
| Idaho | $175,000 | No | $175,000 | $0 | $25,000 | $125,000 | None listed |
| Illinois | $50,000 | No | $50,000 | $50,000 | $150,000 | $250,000 | None listed |
| Indiana | $22,750 | No | $22,750 | $77,250 | $177,250 | $277,250 | None listed |
| Iowa | Unlimited | No | Unlimited | $0 | $0 | $0 | ½ acre urban / 40 acres rural |
| Kansas | Unlimited | No | Unlimited | $0 | $0 | $0 | 1 acre urban / 160 acres rural |
| Kentucky | $5,000 | Yes | $31,575 | $68,425 | $168,425 | $268,425 | None listed |
| Louisiana | $35,000 | No | $35,000 | $65,000 | $165,000 | $265,000 | 5 acres urban / 200 acres rural |
| Maine | $94,300 | No | $94,300 | $5,700 | $105,700 | $205,700 | None listed |
| Maryland | $31,575 | No | $31,575 | $68,425 | $168,425 | $268,425 | None listed |
| Massachusetts | $1,000,000 declared ($125,000 automatic) | Yes | $1,000,000 | $0 | $0 | $0 | None listed |
| Michigan | $51,150 | Yes | $51,150 | $48,850 | $148,850 | $248,850 | None listed |
| Minnesota | $540,000 | Yes | $540,000 | $0 | $0 | $0 | 160 acres |
| Mississippi | $75,000 | No | $75,000 | $25,000 | $125,000 | $225,000 | 160 acres |
| Missouri | $15,000 ($40,000 from Jan. 1, 2027) | No | $15,000 | $85,000 | $185,000 | $285,000 | None listed |
| Montana | $425,800 c | No | $425,800 | $0 | $0 | $0 | None listed |
| Nebraska | $120,000 | No | $120,000 | $0 | $80,000 | $180,000 | 2 lots urban / 160 acres rural |
| Nevada | $605,000 | No | $605,000 | $0 | $0 | $0 | None listed |
| New Hampshire | $120,000 | Yes | $120,000 | $0 | $80,000 | $180,000 | None listed |
| New Jersey | None (federal only) | Yes | $31,575 | $68,425 | $168,425 | $268,425 | None listed |
| New Mexico | $150,000 | Yes | $150,000 | $0 | $50,000 | $150,000 | None listed |
| New York | $102,400 to $204,825 | Yes | $102,400 | $0 | $97,600 | $197,600 | county-based |
| North Carolina | $35,000 | No | $35,000 | $65,000 | $165,000 | $265,000 | None listed |
| North Dakota | $150,000 | No | $150,000 | $0 | $50,000 | $150,000 | None listed |
| Ohio | $182,625 | No | $182,625 | $0 | $17,375 | $117,375 | None listed |
| Oklahoma | Unlimited | No | Unlimited | $0 | $0 | $0 | 1 acre urban / 160 acres rural |
| Oregon | $158,300 | Yes | $158,300 | $0 | $41,700 | $141,700 | 1 block urban / 160 acres rural |
| Pennsylvania | None (federal only) | Yes | $31,575 | $68,425 | $168,425 | $268,425 | None listed |
| Rhode Island | $500,000 | Yes | $500,000 | $0 | $0 | $0 | None listed |
| South Carolina | $76,125 v | No | $76,125 | $23,875 | $123,875 | $223,875 | None listed |
| South Dakota | Unlimited | No | Unlimited | $0 | $0 | $0 | 1 acre urban / 160 acres rural |
| Tennessee | $35,000 | No | $35,000 | $65,000 | $165,000 | $265,000 | None listed |
| Texas | Unlimited | Yes | Unlimited | $0 | $0 | $0 | 10 acres urban / 100 to 200 acres rural |
| Utah | $53,700 | No | $53,700 | $46,300 | $146,300 | $246,300 | 1 acre |
| Vermont | $125,000 | Yes | $125,000 | $0 | $75,000 | $175,000 | None listed |
| Virginia | $50,000 | No | $50,000 | $50,000 | $150,000 | $250,000 | None listed |
| Washington | $125,000 or county median, if higher | Yes | $125,000 | $0 | $75,000 | $175,000 | county-based |
| West Virginia | $35,000 | Yes | $35,000 | $65,000 | $165,000 | $265,000 | None listed |
| Wisconsin | $75,000 | Yes | $75,000 | $25,000 | $125,000 | $225,000 | up to 40 acres |
| Wyoming | $100,000 | No | $100,000 | $0 | $100,000 | $200,000 | None listed |
c Calculated from the statute’s inflation formula; no agency publishes the adjusted figure. Arizona indexes a $400,000 base to CPI each January. California’s floor and cap ($300,000 and $600,000 in statute) adjust each year for California CPI; the range shown reflects 2026 adjustments. Montana’s $350,000 base (2021) rises 4% a year. v South Carolina’s figure is the most recent official adjustment (July 1, 2024); the state adjusts in even years. a Arkansas’s unlimited constitutional homestead applies to married filers and heads of family. Missouri rises to $40,000 for cases filed on or after January 1, 2027. Massachusetts protects $125,000 automatically and $1,000,000 with a recorded declaration. For county-based states (California, New York, Washington), the analysis uses the statewide floor.
Why Texas Protects More Than Almost Anywhere Else
Texas doesn’t cap homestead protection by dollars. It caps it by land. That one design choice, written into the state constitution, is why a $900,000 house in Houston gets the same protection as a $150,000 one in Waco.
No dollar ceiling
Texas Constitution art. XVI, §50 shields a family’s or single adult’s homestead from forced sale for all debts except a short list: purchase money, property taxes, owelty, qualifying refinances, home improvement contracts, home equity loans, reverse mortgages and manufactured home conversions.
Acreage is the real limit
Under Tex. Prop. Code §41.002, an urban homestead covers up to 10 acres. A rural homestead covers up to 200 acres for a family or 100 acres for a single adult.
What counts as “urban”
Property is urban if it sits in a city, its extraterritorial jurisdiction or a platted subdivision, has police and fire protection, and gets at least three of these from a city: electric, natural gas, sewer, storm sewer or water (§41.002(c)).
Sale proceeds stay protected for 6 months
Tex. Prop. Code §41.001(c) keeps the cash from selling a homestead off-limits to creditors for six months after the sale. That clock matters a lot for anyone selling during Chapter 13.
One catch people miss. The exemption protects equity. It doesn’t protect against the mortgage lender, the tax office or a home equity lender. Those debts still get paid at closing. And Texas filers can choose the federal exemption list instead ($31,575 for the home), but not both. For a homeowner with real equity, the Texas list almost always wins.
Two Federal Rules That Can Cap a Texas Homestead
Unlimited isn’t always unlimited. Federal bankruptcy law puts two time-based fences around state exemptions, and both catch people who recently moved or recently bought.
The 730-day rule: new Texans may not get Texas exemptions
Under 11 U.S.C. §522(b)(3)(A), a filer uses the exemption laws of the state where they were domiciled for the 730 days (two years) before filing. Someone who moved to Texas 18 months ago generally uses the old state’s rules, based on where they lived for most of the 180 days before that two-year window.
The 1,215-day rule: a $214,000 cap on recently acquired equity
Under §522(p), homestead equity acquired within 1,215 days (about 3 years and 4 months) before filing is capped at $214,000 when the filer uses state exemptions. That figure took effect April 1, 2025, per the Judicial Conference’s Federal Register notice, and the next adjustment is scheduled for April 1, 2028. Equity rolled over from a previous home in the same state generally doesn’t count toward the cap. The calculator above applies this cap when the box is checked.
Texas Chapter 13 by District: Filings and Sale Rules
Texas has four federal bankruptcy districts, and each one handles a home sale in Chapter 13 a little differently. Here’s the filing volume from the U.S. Courts’ Table F-2 for the 12 months ending June 30, 2026.
| District | Major cities | All filings | Chapter 13 | Chapter 13 share |
|---|---|---|---|---|
| Northern | Dallas, Fort Worth, Amarillo, Lubbock | 13,937 | 4,690 | 33.7% |
| Southern | Houston, Galveston, Corpus Christi | 12,475 | 4,045 | 32.4% |
| Western | San Antonio, Austin, El Paso, Waco | 9,121 | 2,753 | 30.2% |
| Eastern | Plano, Tyler, Beaumont | 6,696 | 2,539 | 37.9% |
| Texas total | 4 districts | 42,229 | 14,027 | 33.2% |
| United States | 94 districts | 608,511 | 215,490 | 35.4% |
Southern District (Houston)
Sales of exempt property run through Form 13-106, an ex parte motion under the local plan. The filer sends the trustee the final closing statement within 14 days of closing. Texas homestead proceeds not reinvested in a new Texas homestead within six months go to the trustee. All three standing trustees post a 10% fee on plan payments as of December 1, 2024 (court posting).
Northern District (Dallas, Fort Worth)
General Order 2026-01, effective February 11, 2026, lets motions to sell go on the trustee’s pre-hearing conference docket and sets a presumed $450 attorney fee for a motion to sell.
Western District (San Antonio, Austin, El Paso, Waco)
Local Rule 6004-1 requires a sale motion to disclose the buyer, any relationship to the seller, the price, costs and liens. In Chapter 13, it must also state whether the trustee and affected secured creditors consent.
Eastern District (Plano, Tyler, Beaumont)
Local Rule 6004 requires sale motions to carry 21-day negative notice language and be served on the full creditor list.
A note on the trustee fee, since it’s often misquoted. Under 28 U.S.C. §586(e), the Chapter 13 trustee’s percentage fee is capped at 10% and comes out of payments made through the plan. It isn’t a fee on the home’s sale price. Proceeds only carry the fee when they’re paid into the plan.
For a Texas seller in Chapter 13, protection is rarely the problem. Timing is. The motion, the trustee review and the six-month clock on proceeds set the pace. Bodebuilders explains how that timeline runs for sellers facing foreclosure in Houston and for complicated sales in Dallas.
Methodology
Question. How much home equity does each state’s homestead exemption protect in bankruptcy, and how much would a filer with a set amount of equity leave unprotected?
Sources. State homestead statutes and constitutions for all 50 states and D.C., plus official adjustment notices where states index for inflation (for example, the Michigan Department of Treasury, Minnesota Department of Commerce, Oregon Judicial Department, Utah State Auditor, New York Department of Financial Services and the Maine Judicial Branch). Federal figures come from 11 U.S.C. §522 and the Judicial Conference adjustment published at 90 FR 8941 (February 4, 2025). Filing counts come from U.S. Courts Table F-2 for the 12 months ending June 30, 2026. District procedures come from each court’s local rules, general orders and forms.
Method. For each jurisdiction, the analysis takes the single-filer homestead amount in effect on October 3, 2026. Where a state allows filers to elect the federal exemptions, the “best option” is the higher of the state amount or the federal homestead amount of $31,575. Exposed equity equals the equity level minus the best option, with a floor of $0. Unlimited states show $0 exposed.
Limitations. This compares homestead exemptions only. It leaves out wildcard exemptions, tenancy by the entirety, age and disability enhancements, married-couple doubling, and the §522(p) cap (except where the calculator applies it). County-based states use the statewide floor. Arizona, California and Montana figures are calculated from statutory formulas. South Carolina reflects its most recent published adjustment. Exemption law changes often; Georgia and Illinois both raised their amounts in 2026.
Updates. Bodebuilders will refresh this page after the next federal adjustment on April 1, 2028, and sooner when a state changes its amount.
How to Cite or Embed This Data
Suggested citation: Reichek, Andrew. “Bankruptcy Homestead Exemption by State: Texas vs. All 50 (2026 Data).” Bodebuilders, October 2026. https://bodebuilders.com/bankruptcy-homestead-exemption-by-state/
Embed the chart (copy and paste):
Homestead Exemption Questions
Which states have an unlimited homestead exemption?
Seven states and D.C. put no dollar cap on homestead equity: Arkansas, Florida, Iowa, Kansas, Oklahoma, South Dakota and Texas, plus the District of Columbia. All but D.C. limit the protected land by acreage or lot size instead, and Arkansas’s unlimited version applies to married filers and heads of family.
How much is the federal homestead exemption in 2026?
The federal homestead exemption under 11 U.S.C. §522(d)(1) is $31,575 per filer, effective April 1, 2025. Married couples filing jointly can each claim it, for $63,150. It’s only available in states that allow filers to choose the federal list, Texas included.
Does the Texas homestead exemption stop a mortgage foreclosure?
No. The Texas homestead exemption protects equity from unsecured creditors, like credit cards and medical bills. It doesn’t stop the mortgage lender, the property tax office or a home equity lender from enforcing their liens.
Can someone who just moved to Texas use the Texas homestead exemption?
Usually not right away. A filer generally needs 730 days of Texas domicile before filing to use Texas exemptions, and equity acquired within 1,215 days of filing is capped at $214,000 when state exemptions are used.
Selling a Texas House During Chapter 13?
Bodebuilders buys houses as-is, works with the trustee’s timeline, and closes when the court approves the sale.
Get a Cash Offer Or call (832) 910-7743, 7 days a weekThis page is general information, not legal advice. Exemption amounts and court procedures change, and the right exemption choice depends on the full case. Talk to a licensed Texas bankruptcy attorney before filing or selling.